Uber Pro Card

Screenshots
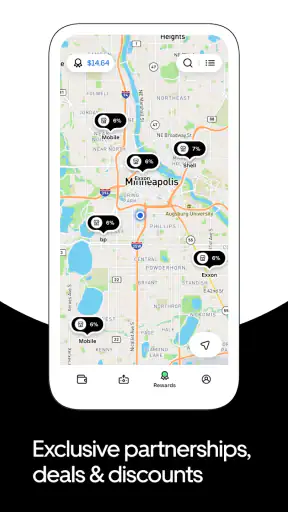
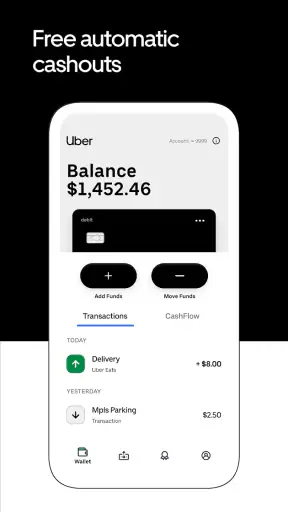
Details
- Rating
- 6.14K reviews
- Version
- 2026.8.2
- Developer
- Branch Messenger
Analysis by Norviv
When I first looked at Uber Pro Card, I understood its appeal quickly: it is a finance app built around helping Uber drivers manage the money they earn from driving. The experience is more focused than a general banking app, because the whole idea is to give drivers a direct place to handle their work-related earnings rather than forcing them to piece everything together across several services.
The app is developed by Branch Messenger and is available free of charge for everyone. It has already passed one million installs, with an average rating of 4.9 from around 82 thousand ratings and more than 6 thousand written reviews. Those figures suggest that it is solving a practical problem for a large number of drivers, although a high store rating should not replace checking whether the app’s workflow fits the way you personally receive and use your income.
My overall impression is that Uber Pro Card works best when you treat it as a dedicated earnings tool, not as a universal replacement for every financial service you already use. It can make the path from completing work to accessing and organizing that money feel more direct. At the same time, anyone expecting a full-featured budgeting platform, a broad investment app, or a traditional bank account with every possible service may find its narrower purpose limiting.
What the first-time experience feels like
The first thing to expect is a product designed around the rhythm of driving work. That matters because driver income is often less predictable than a fixed paycheck. A person may drive more on a weekend, less during a quiet week, or use the app only around another job. A finance tool made for that pattern needs to reduce the amount of manual sorting involved, and this is where the Uber Pro Card concept makes the most sense.
I would not approach it expecting a long list of financial products. Instead, I would ask a simpler question: can this app make my Uber earnings easier to access and keep track of? If the answer is yes, the focused design is an advantage. You are not opening an app to browse unrelated financial features; you are opening it to deal with money connected to driving.
The store summary, “Keep more of what you earn,” sets the tone, but I found it more useful to interpret that as a goal rather than a promise. Keeping more of your earnings depends on how you manage fuel, maintenance, taxes, personal spending, and transfers. The app can support a cleaner workflow, but it cannot make the underlying costs of driving disappear.
That distinction is important for first-time users. A dedicated earnings card can make money feel more available, which is convenient, but convenience can also make it easier to spend work income before accounting for expenses. I recommend deciding in advance how much of each payment is genuinely available for everyday use and how much should remain reserved for vehicle costs and taxes.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Who is likely to benefit most
The strongest fit is an active Uber driver who wants work earnings separated from a personal checking account. Keeping those flows apart can make it easier to review what driving brought in and what you need to set aside. It is also useful for someone who prefers a straightforward mobile experience over managing a complicated collection of banking tools.
It may also suit a part-time driver who wants a dedicated place for driving income without changing the account used for rent, subscriptions, or household bills. In that situation, the card can act as a boundary: driving money enters one space, while personal finances remain elsewhere. That separation is a small organizational decision, but it can make monthly review much less confusing.
I would be more cautious if you want one account to handle a complete financial life. A traditional bank may be a better choice for people who need a broad set of account types, extensive branch support, or a long-established system for joint household finances. Likewise, a budgeting app may be better for someone whose main goal is category tracking across many accounts rather than managing driver earnings.
Setting it up without making the process harder than it needs to be
Uber Pro Card runs on Android with a minimum operating system requirement of version 10, and its current version is 2026.8.2. Before installing, I would check the phone’s software version and make sure the device has enough room for a finance app and its updates. That sounds basic, but it prevents a frustrating start, especially if the app is being installed just before a driving shift.
Because this is a financial product, I would also begin with the same care I use for any money-related app. I would install it from the official app marketplace, use an email address and phone number I can reliably access, and avoid rushing through identity or account screens simply to reach the home page. A small mistake in contact details can become annoying later when trying to recover access.
The most useful preparation is to have the information connected to your Uber driving activity available before starting. I would not assume that downloading the app alone completes the relationship between the driver account and the card. Read each setup screen carefully, confirm that the correct account is being used, and pause if a detail does not match what you expect.
For security, I recommend using a unique passcode or password rather than reusing the one from another service. If the app offers device security options during setup, I would enable the strongest option that remains convenient enough to use every day. A financial app needs to be quick, but speed should not come from leaving the account poorly protected.
What to check before relying on it
After setup, I would spend a few minutes learning where the important information appears. Look for the current available balance, recent activity, card-related controls, and any area that explains how earnings reach the account. The goal is not to memorize every screen. It is to know where you would go when a payment looks unfamiliar, when the balance seems unexpected, or when you need to review a recent transaction.
I would also make a small personal checklist before using the card regularly:
- Confirm that the account identity and driver details are correct.
- Review how incoming earnings are displayed and when they become usable.
- Check how to recognize ordinary spending versus incoming work income.
- Decide how often you will move money aside for fuel, maintenance, and taxes.
- Keep a second payment method available while you are still learning the workflow.
That last point is not a criticism of the app. It is sensible with any new financial service. Your first few days should be about confirming that the experience behaves as you expect, not about making it the only way you can pay for an important purchase.
Reaching the first meaningful success
For a first-time user, the first meaningful success is not merely opening the app. It is completing one full cycle with confidence: checking that earnings are visible, understanding the available balance, and using the card or account for a planned expense without wondering where the money came from.
A realistic example would be a driver who finishes several trips after work, opens the app later that day, and separates the balance mentally into three parts. One part is for immediate personal spending, another is reserved for fuel and vehicle upkeep, and the last is left untouched for tax planning. The app does not make those decisions for you, but a dedicated earnings view can make the separation easier to maintain.
For the first purchase, I would choose something ordinary and easy to verify, such as a planned grocery item or a fuel stop, rather than a large urgent payment. Immediately afterward, check the activity screen and compare the transaction with the receipt. This gives you a practical understanding of how a purchase appears, how the balance changes, and where to look if you need to investigate something later.
That small test is more valuable than simply exploring menus. It turns the app from an unfamiliar download into part of a repeatable routine. Once you know how a normal payment looks, unusual activity becomes easier to spot. You also learn whether you personally prefer using the card directly or moving money to another account for broader spending.
A workflow that can save time later
My preferred workflow would be to review the app at a fixed point after driving rather than checking it constantly. For example, after finishing a shift, I would confirm the latest earnings, note any work expenses separately, and decide what portion is safe to spend. This avoids confusing a temporary balance with actual disposable income.
Another useful habit is to keep a simple external record of driving costs. Even if the app shows your earnings clearly, it is not a substitute for your own mileage, fuel, repair, and tax notes. The non-obvious advantage of pairing the card with a basic spreadsheet or notes system is that you can compare money received with the cost of producing it. That gives you a more honest view of whether a busy week was genuinely profitable.
I would also avoid using the card for every personal purchase immediately. During the first month, limiting it to predictable categories makes the activity easier to understand. Once you are comfortable with the balance and transaction history, you can decide whether broader use actually simplifies your finances or merely spreads them across another account.
Where new users can become confused
The most likely confusion is the difference between earnings connected to driving and money that is truly free to spend. A balance can look healthy while upcoming fuel, maintenance, insurance, or tax obligations remain outside the app’s immediate view. I would treat the displayed amount as an account balance, not as a personalized spending recommendation.
Timing can also be misunderstood. Drivers may expect every earning-related change to appear exactly when they finish a trip or expect every amount shown to be immediately usable. If a balance or activity entry looks different from your expectation, compare it with the relevant Uber records and read the transaction details before assuming something is wrong.
Another common issue is mixing card activity with the rest of your finances. If you use the card for personal purchases, the transaction list can become harder to interpret. My solution would be to create a clear rule: use it mainly for driving-related money and a small number of planned personal expenses, or use it broadly but review it on a fixed schedule. The worst approach is using it randomly and then trying to reconstruct the month from memory.
People may also wonder whether this app replaces their existing bank. In my view, that depends on what “replace” means. If you mean “give me a dedicated way to manage money earned from Uber driving,” it may do that job well. If you mean “handle every household payment, savings goal, financial record, and account relationship,” I would keep a broader banking setup alongside it.
When another option makes more sense
A conventional bank account is likely better for someone who values a wider financial relationship and already has an organized system for direct deposits, bills, savings, and shared expenses. A separate prepaid or debit solution may be preferable for a person who wants a general-purpose spending card unrelated to one source of income. A budgeting service is the stronger choice when the main challenge is seeing all spending categories across multiple accounts.
Uber Pro Card is also not the right answer for a driver who dislikes managing more than one financial destination. If adding another balance creates more work than it removes, the convenience of a dedicated earnings tool may not outweigh the extra review. The best setup is the one you can understand at a glance and maintain consistently, not necessarily the one with the most specialized branding.
Privacy and security habits matter just as much as the app’s interface. I would keep the phone protected, avoid signing in on shared devices, review activity regularly, and contact the appropriate support channel promptly if a transaction does not look familiar. These are practical safeguards, especially when the account is connected to income from regular work.
How I would use it after the first week
Once the initial test is complete, I would give the app a defined job. My version would be: receive or manage driving earnings, cover selected work-related spending, and provide a clean record for weekly review. I would not ask it to become my entire financial system unless its day-to-day workflow genuinely proved easier than the alternatives I already use.
At the end of each week, I would compare the activity in the app with my driving schedule and personal notes. I would look for three things: whether the money I expected arrived, whether spending is recognizable, and whether the remaining balance still makes sense after setting aside operating costs. This review takes less time when transactions are kept purposeful rather than mixed with dozens of unrelated purchases.
A second advanced habit is to use the account as a boundary for irregular income. Instead of treating a busy week as permission to increase everyday spending immediately, I would wait until the week’s vehicle costs and tax reserve are accounted for. That turns the app into part of a decision process rather than just a place where money appears.
For part-time drivers, a monthly review may be enough. For full-time drivers, weekly checks are more practical because fuel and maintenance can change the real value of earnings quickly. The right schedule depends on how often you drive, but the principle stays the same: review the account when you can still act on what you see.
What the reputation tells me, and what it does not
The app’s strong store reception is encouraging. A 4.9 average from around 82 thousand ratings and its reach beyond one million installs show that many users find the product worthwhile. I see that as evidence of practical usefulness, not proof that every driver will have the same experience. Financial routines are personal, and an app can be highly effective for one person while adding unnecessary complexity for another.
The Everyone age rating also makes the app broadly approachable from a content perspective, but adults should still treat it as a serious financial tool. A simple interface does not remove the need to understand balances, protect access, and plan for expenses. The app’s current version, 2026.8.2, is another reason to keep it updated through the normal app marketplace, particularly when using a product connected to earnings.
What I appreciate most is the focused purpose. What I would watch most carefully is the temptation to confuse easy access with extra income. The card can help organize money you earn; it cannot decide whether a purchase is affordable after the real cost of driving is included.
After using it as a dedicated earnings companion, I would recommend Uber Pro Card to an Uber driver who wants a clearer separation between driving income and personal banking. I would start slowly, verify one normal transaction, establish a weekly review habit, and keep records for expenses outside the app. That path makes the first success concrete without asking you to rebuild your entire financial life on day one.
My final view is positive but deliberately practical: Uber Pro Card is most valuable when its specialization reduces financial clutter. If that is the problem you are trying to solve, the free app from Branch Messenger is worth trying. If you need a complete banking ecosystem or a detailed cross-account budgeting system, pair it with the service that handles those jobs better rather than expecting one driver-focused app to do everything.
Frequently Asked Questions
01What is Uber Pro Card, and who can use it?
Uber Pro Card is a financial account and debit card designed for eligible Uber drivers and delivery partners. It can help you receive earnings, manage money, and access features connected to your work on the Uber platform. Availability, eligibility, and benefits may vary by country, driver status, and current Uber or partner-banking requirements.
02How do I sign up for Uber Pro Card?
You generally begin registration through the Uber Driver app, an invitation, or the official Uber Pro Card application process, depending on your location. You may need to provide personal information, verify your identity, and accept the account terms. Approval is not guaranteed, so review eligibility requirements carefully before submitting an application.
03When do my Uber earnings arrive on the Pro Card?
One of the main advantages of Uber Pro Card is that eligible earnings may be deposited automatically after completing trips or deliveries, rather than waiting for a traditional weekly payout. The exact timing can depend on your market, account setup, transaction processing, and whether the earnings qualify. Always check the app for the latest payout details.
04Are there fees for using Uber Pro Card?
Uber Pro Card may offer useful features without certain common account fees, but costs can still apply depending on the service you use. Possible charges may involve out-of-network ATM withdrawals, card replacement, international transactions, or other optional services. Fee policies can change, so read the current pricing information in the app before relying on the card.
05Is Uber Pro Card a bank account, and is my money protected?
Uber Pro Card functions as a financial account connected to a debit card, but the exact banking arrangement depends on the country and issuing partner. It is not necessarily the same as opening a conventional account directly with a local bank. Before depositing or spending money, review the account agreement, available protections, limits, and support options for your region.


